Assessing opportunities in New Zealand’s office sector
08 September 2026
Insight
08 September 2026
New Zealand’s Office Property Trends
Categories:
Authors
Chris Dibble
Monish Khan
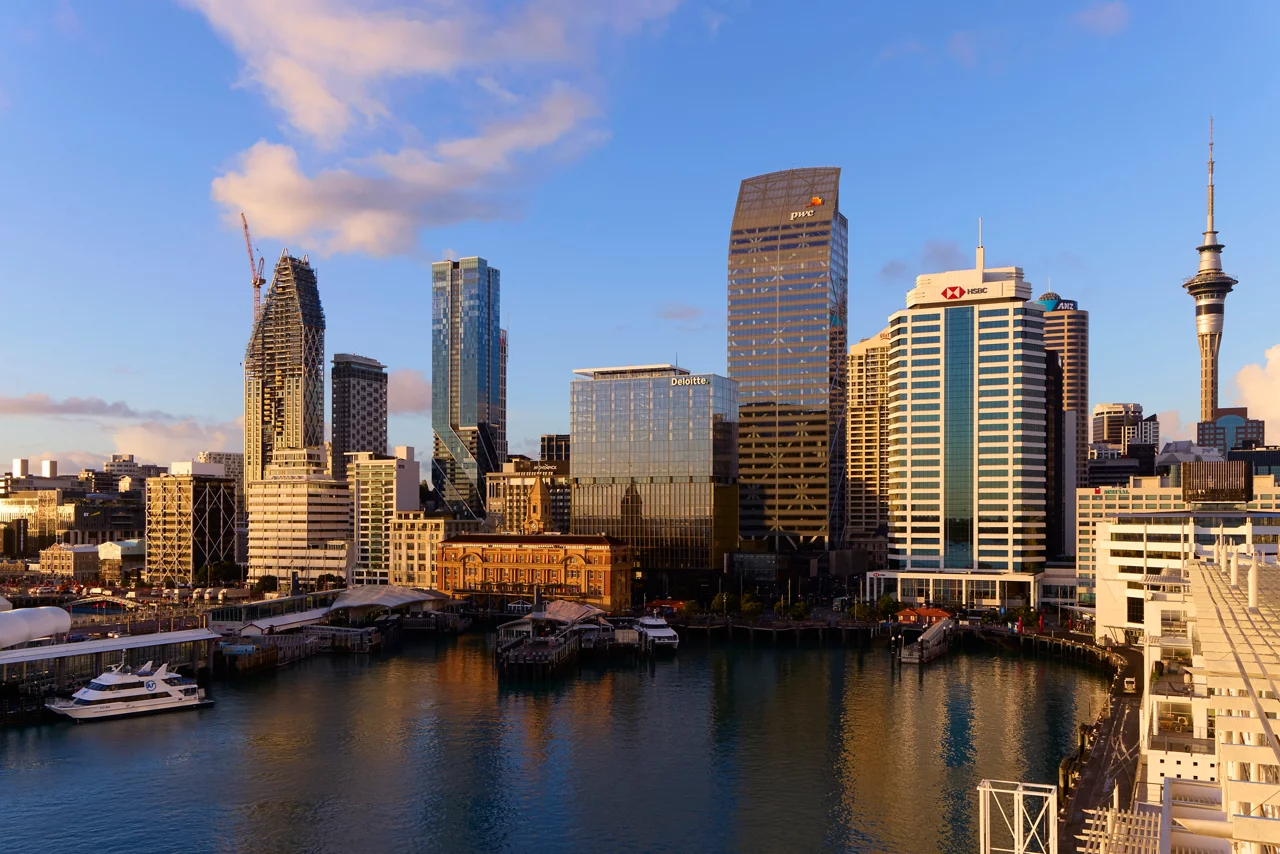
Image courtesy of Precinct Properties.
Key highlights
- Offshore interest picks up: Major transaction numbers remained limited over 2024/25, but increased core and value-add activity from local and offshore investors in 2026 signals a return in confidence as conditions improve.
- Prime rental growth continues: Prime rents continue to edge up in major cities, although rising OPEX is weighing on gross rents in some markets. Rent reversion and the need to reach economic rent levels suggest further growth is likely.
- Buoyant economic fundamentals: New Zealand's population and GDP growth rates are projected to be strong through to 2035, providing a solid foundation for the office sector.
- Flight to quality intensifies: Overall vacancy rates across New Zealand remain elevated, but persistent demand for well-located, high-quality buildings is keeping prime vacancy rates low. Prime buildings with sustainability certifications show lower vacancy rates.
- Development proposals up: Approximately 313,000 sqm is under development and refurbishment across the three main cities, representing substantial investment in future-ready office space.
- AI influence not uniform: AI's impact on office demand varies by location, city and industry, with rising adoption reshaping fit-outs towards more collaborative, tech-enabled space.
Economic fundamentals underpin long-term demand
New Zealand's projected average annual GDP growth of around 2.5% through to 2035, combined with population growth around 1.0% per year, provides solid foundations for office demand. Office-related sectors account for approximately 20% of GDP and support over 200,000 jobs across Auckland, Wellington and Canterbury, with both business and employment counts showing consistent growth since 2015.
Net migration moderated through 2024 and 2025 but is expected to trend upward again, supporting workforce expansion and office-using employment. The breadth of office-dependent sectors spanning finance and insurance, professional services, information technology, public administration and business services creates diversified demand across multiple occupier types and business scales.
Major development projects include Auckland's Te Pūmanawa o Tāmaki at 29 Customs Street West (72,500 sqm, 2032), 35 Graham Street (35,000 sqm, 2028), and refurbishment of Bledisloe House, with the AXA Centre in Wellington. Building consent issuance is below the long-term average of approximately 165,000 sqm annually.
Rental growth and quality divergence shape occupier decisions
Auckland premium space currently achieves approximately $950 per sqm per annum, with A-grade at $650 per sqm. Wellington premium space sits at $850 per sqm, with A-grade at $600 per sqm. Rising operating expenses create pressure on net effective rents in some markets, while rent reversion on older leases continues to support upward movement.
The proportion of prime stock has increased across all three major CBDs. Auckland's prime stock now represents 56% of total CBD supply, Wellington 37%, and Christchurch 48%, reflecting both new development and repositioning of existing assets. This shift towards higher-quality inventory supports the flight to quality trend.
Workplace evolution and development activity reshape supply
Workplace trends are being reshaped by AI adoption and collaboration requirements. JLL's workplace survey reveals that 91% of organisations are providing AI tools to employees, with 66% using these tools daily or regularly. When asked to rank workplace priorities, employees consistently placed location for ease of travel, quality of space, and wellbeing contributions as top factors.
Auckland CBD office ownership
Transaction activity signals returning confidence. The first half of 2026 saw significant deals including the $600 million sale of 15 Customs Street West in Auckland, the $205 million acquisition of 1-26 Jellicoe Street, and the $74.5 million purchase of 99 Albert Street. Office yields in Auckland range from 5.50% to 6.63%, with Wellington at 5.75% to 7.15% and Christchurch at 6.15% to 6.75%.
The office sector's evolution towards higher-quality, technology-enabled, collaborative workspaces continues to support premiums for buildings that meet these requirements. As organisations refine workplace strategies and AI adoption matures, demand for flexible, well-located, sustainable space will remain resilient, while older, lower-specification buildings face increasing challenges.
Download the full report: New Zealand Office Property Trends.
Want to know what's happening in New Zealand's other commercial property sectors?
- Read our New Zealand Industrial Property Trends
- Read our New Zealand Retail Property Trends
Want to learn more?
Get in touch with our team to find out how we can support your real estate strategy with market insights and strategic advice.
Liam Matheson
Associate Director, Office Leasing Advisory