Market maturation, cost inflation, and competitive dynamics shaping sector growth
30 September 2026
Insight
30 September 2026
Saudi Arabia construction market review, H1 2026
Categories:
Authors
Maroun Deeb
Clarke Morton-Shepherd
Taimur Khan
Rana Mira
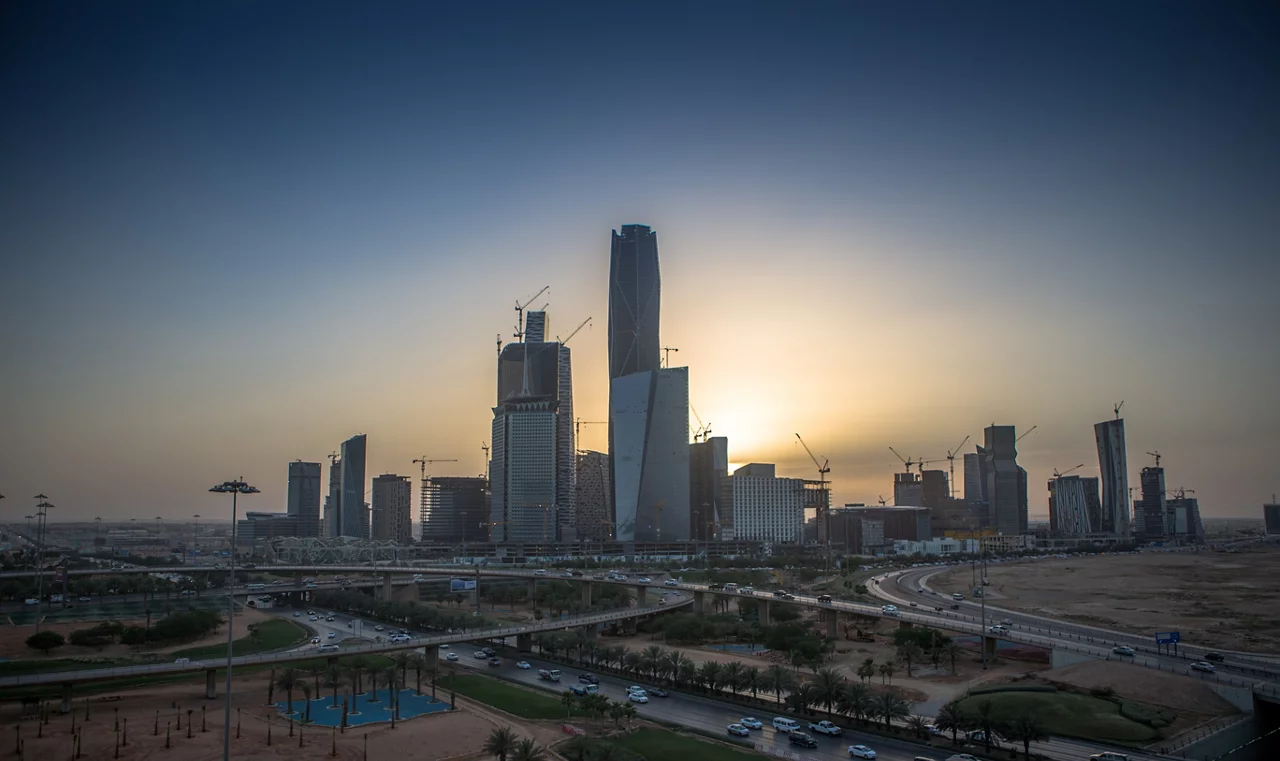
Saudi Arabia's construction sector is entering a phase of more measured and sustainable growth following a period of unprecedented expansion. While development activity remains strong, market maturation, regulatory reforms, and increased private sector participation are reshaping the industry landscape and sustaining momentum across key sectors.
Construction costs continue to face upward pressure due to ongoing supply chain disruptions, geopolitical tensions, and rising commodity prices. Escalating costs for key materials such as copper, aluminum, steel, and fuel, combined with longer lead times and higher logistics expenses, have contributed to a revised Tender Price Inflation (TPI) forecast of approximately 5.0% for 2026, up from a previous forecast of 4.0%.
Despite inflationary pressures, intense competition among contractors is helping absorb part of the cost escalation through compressed margins, particularly across PPP-led opportunities and large-scale developments. Looking ahead, the market is expected to stabilise further in 2027 as supply chains gradually normalise and competitive market dynamics persist.